When it comes to pension planning, you may have more flexibility than you realise.
If you have not used your full pension annual allowance in previous tax years, carry forward could allow you to make larger pension contributions now while making use of unused allowance from earlier years.
For the right person, this can be a valuable financial planning opportunity.
What is pension carry forward?
The pension annual allowance is normally the maximum amount that can be contributed to your pensions each tax year before an annual allowance tax charge may apply.
For the 2026/27 tax year, the standard annual allowance is £60,000, although some people may have a lower allowance depending on their circumstances.
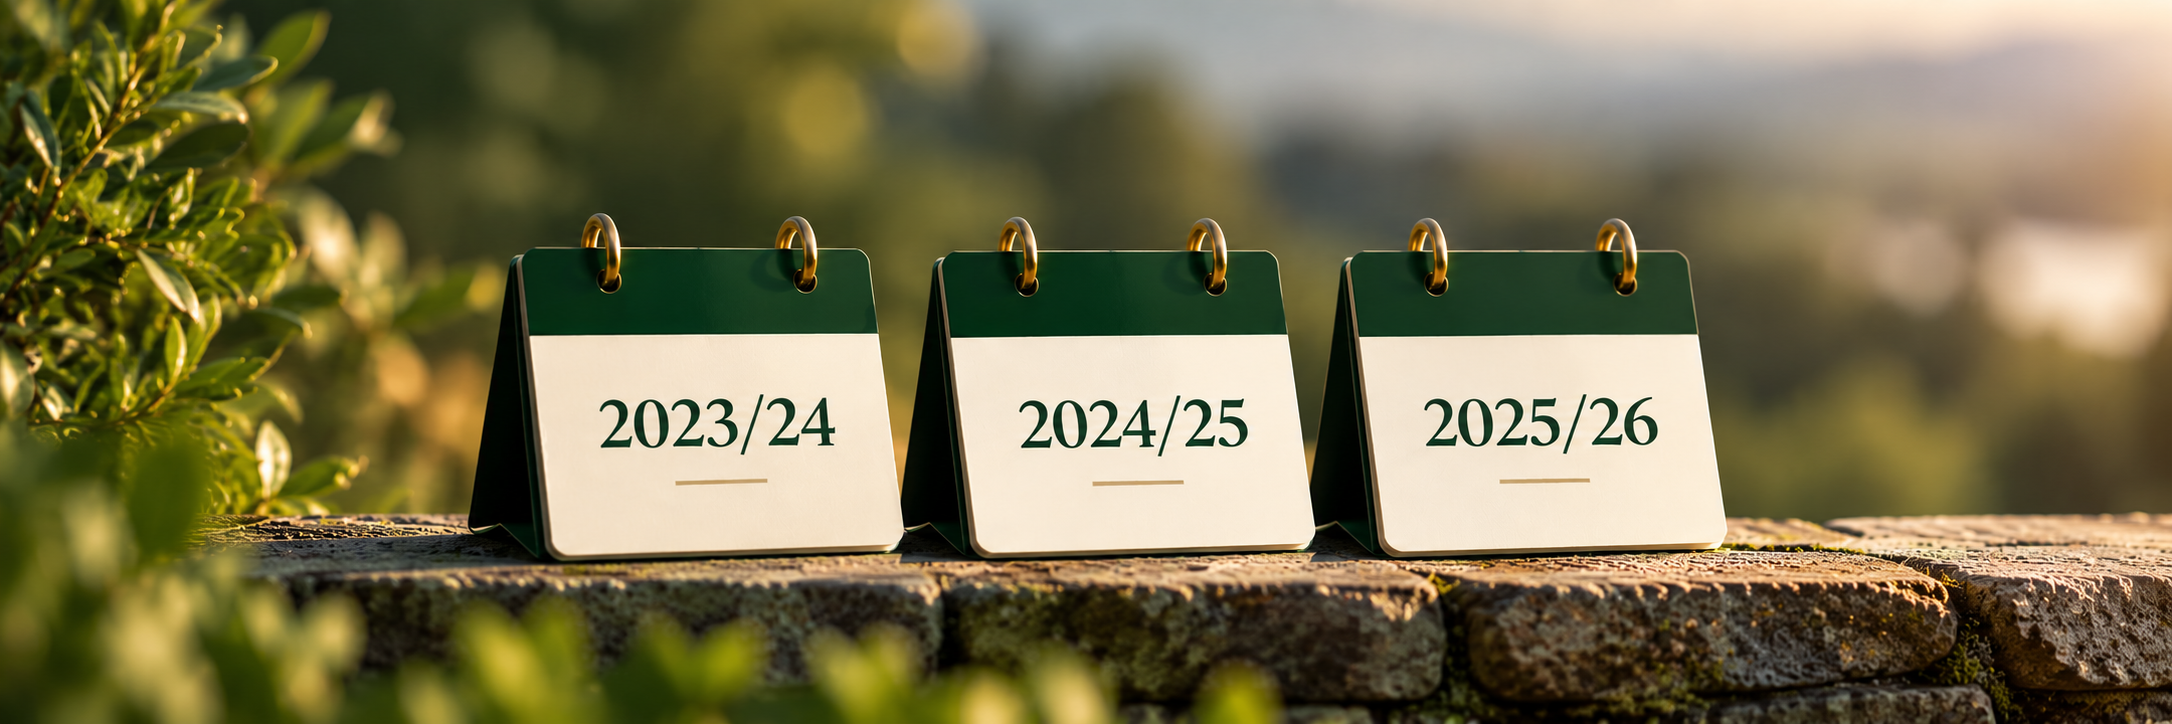
Carry forward allows you to potentially use unused annual allowance from the previous three tax years, in addition to your current year's allowance.
For 2026/27, this means looking back at unused allowance from:
Why could carry forward be useful?
There are many reasons why someone might want to make a larger pension contribution.
Perhaps you've received a bonus, your income has increased, you've sold a business or investment, or you simply haven't been maximising pension contributions in previous years.
Carry forward could provide an opportunity to put more towards your retirement than the standard annual allowance would otherwise permit.
It may be particularly relevant for higher earners and business owners who have the means to make larger pension contributions.
Do you qualify?
This is where things can become more complicated.
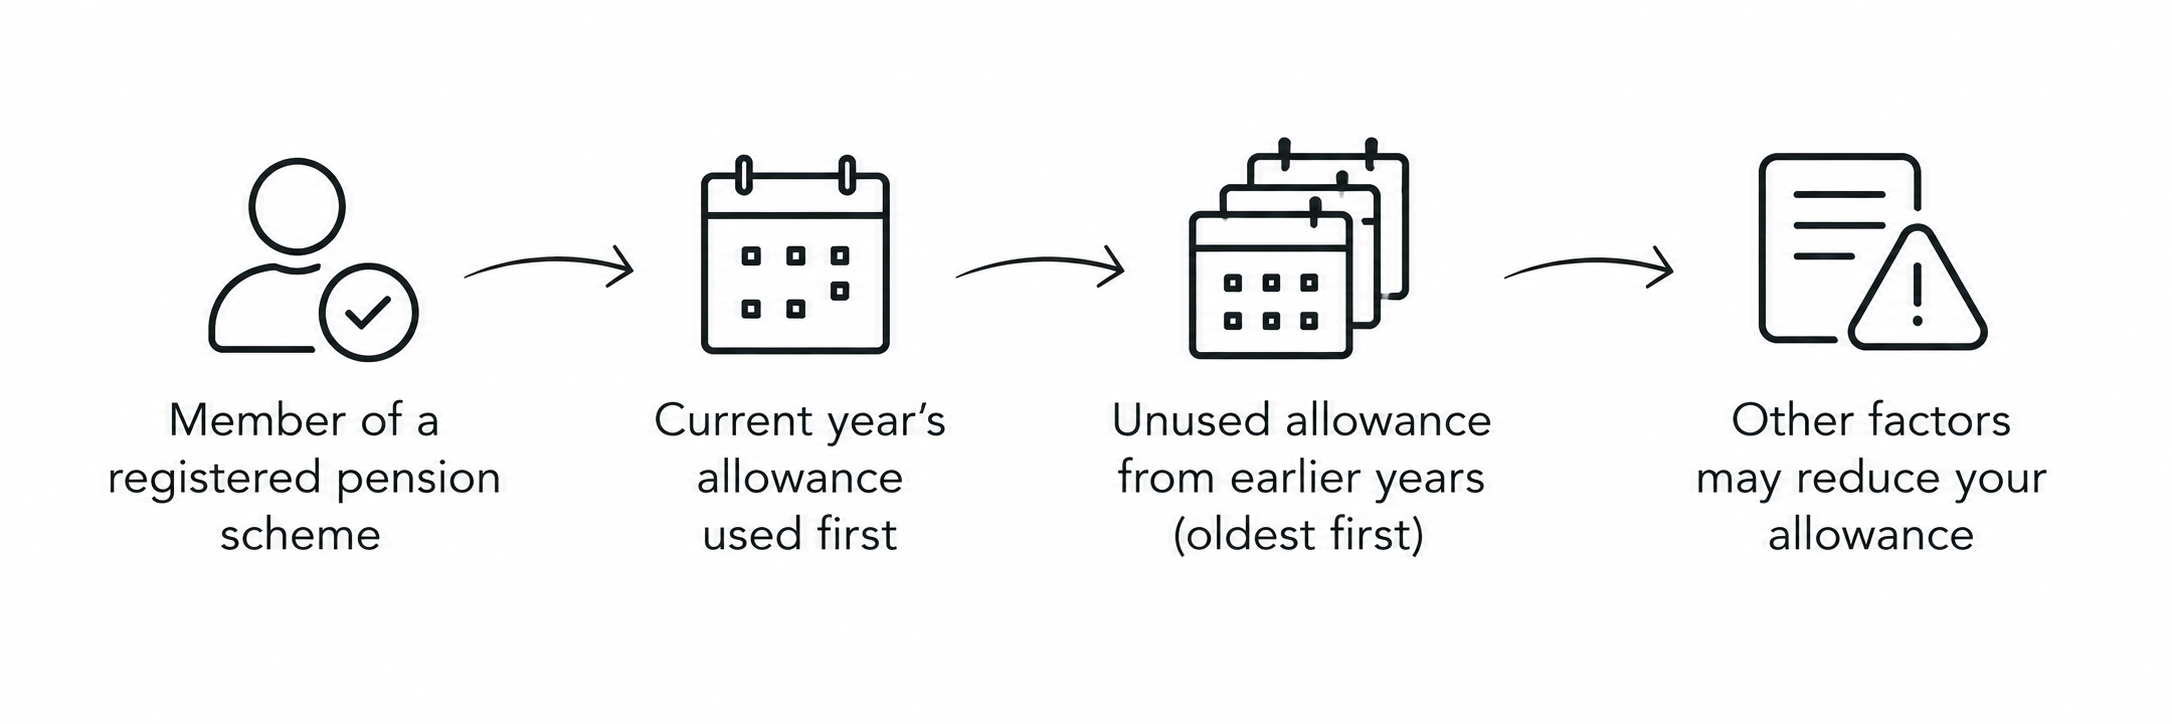
You generally need to have been a member of a registered pension scheme in the tax year you want to carry forward from.
Your current year’s annual allowance is used first.
Unused allowance from previous years is then used, starting with the earliest available tax year.
Your annual allowance may be reduced if you have a high income.
Flexibly accessing pension benefits can affect the allowance available to you.
The Money Purchase Annual Allowance (MPAA) may apply and can place additional restrictions on carry forward.
Don't let valuable allowances disappear
Unused annual allowance does not remain available indefinitely. Carry forward generally only reaches back three tax years, so an older unused allowance can fall out of the available window as you move into a new tax year.
That doesn't mean you should rush into making a pension contribution simply to use an allowance.
Instead, it is a good reason to regularly review your pension planning and understand what allowances may be available to you.
Advice can make the difference
Carry forward can be extremely useful, but pension contributions should form part of your wider financial plan.
Before making a significant contribution, it is important to understand how much unused allowance you actually have, whether any restrictions apply and whether the contribution is appropriate for your circumstances.
At Universal Finance, we can review your existing pensions, previous contributions and current financial position to help you understand whether carry forward could be relevant to you.
You may have unused pension allowances available. The important thing is knowing how, and when, to use them.
This article is for general information only and does not constitute personal financial, investment or tax advice. Pension and tax rules can change, and their application will depend on individual circumstances. Seek appropriate professional advice before making pension contributions.